Tue 31 Oct 2017, 09:01 GMT

Oil and fuel oil hedging market update


By the Oil Desk at Freight Investor Services.


Brent closed up $0.46 last night to $60.90 and WTI closed at $54.15, up $0.25. It really is a fickle old market this oil one isn't it? Momentum seems to be carrying this market on and on. But the market isn't as complicated as people think. In fact, it is relatively simple. Allow me to explain. The way many people treat the market is like that pretentious numpty who for lunch orders a wild fillet of something endangered, served on a bed of something foraged covered with a jus made from wild kelp in the deepest ocean. Whereas actually the market is as simple as a freshly picked blackberry. Basically, if OPEC cancel the agreement or reduce the levels of the cuts, we could rapidly see 1.8 million barrels reappearing in the market. 2018 would go from a predicted deficit of around 260,000 barrels to a surplus of close to 1.5 million barrels. Prices would undoubtedly collapse as a consequence. The current "debate" and discussions between delegates as to whether the cuts will be extended is a mere device to keep everyone's attention on the subject. Funds are jumping on the November OPEC bandwagon and buying into the seemingly bullish notion that extending the cuts will come as a "shock". As my colleague pointed out this morning: every time one reads that "Oil longs are at record highs" it is always the best signal to sell sell selll! I mentioned before that the market is about as fractured as David Busst's leg, and real proper fundamentals are not currently part of anybody's strategy when it comes to Brent futures.

Fuel Oil Market (October 30)

The front crack opened at -8.45, strengthening to -7.90 across the day. The Cal 18 was valued at -8.10.

Elevated trading activity in the physical fuel oil market in the Singapore window saw cash premiums of the 380-cst high-sulphur fuel oil rise, snapping three straight sessions of declines

Sentiment in the paper markets also improved at the start of the week with the near-dated fuel oil time spreads and cracks firming on Monday, recovering some of the losses seen in the previous week

The stronger cracks come despite rising Brent crude prices which broke past $60 a barrel on Friday on support among the world's top producers for extending a deal to rein in output and as the dollar retreated from threemonth peaks. Strong refining margins will be sustained for the next couple of years given a tight balance outlook on the back of persistently slow capacity expansions.

Economic Data/Events: (UK times)

* 10am: Eurozone GDP SA y/y for 3Q, advance, est. 2.4% (prior 2.3%)

* 1:45pm: U.S. Chicago business barometer SA for Oct., est. 60 (prior 65.2)

* 2pm: U.S. Conference Board consumer confidence SA for Oct., est. 121.3 (prior 119.8)

* 6pm: U.S. EIA releases Petroleum Supply Monthly and related data, including August crude, natgas production

* 8:30pm: U.S. API issues weekly oil inventory report

Singapore 380 cSt

Nov17 - 351.75 / 353.75

Dec17 - 350.25 / 352.25

Jan18 - 348.25 / 350.25

Feb18 - 346.75 / 348.75

Mar18 - 345.50 / 347.50

Apr18 - 344.25 / 346.25

Q1-18 - 347.00 / 349.00

Q2-18 - 343.00 / 345.00

Q3-18 - 338.75 / 341.25

Q4-18 - 334.75 / 337.25

CAL18 - 338.75 / 341.75

CAL19 - 307.75 / 312.75

CAL20 - 277.75 / 284.75

Singapore 180 cSt

Nov17 - 356.75 / 358.75

Dec17 - 355.25 / 357.25

Jan18 - 353.50 / 355.50

Feb18 - 352.75 / 354.75

Mar18 - 351.75 / 353.75

Apr18 - 350.75 / 352.75

Q1-18 - 352.75 / 354.75

Q2-18 - 349.25 / 351.25

Q3-18 - 345.00 / 347.50

Q4-18 - 342.00 / 344.50

CAL18 - 345.25 / 348.25

CAL19 - 316.25 / 321.25

CAL20 - 287.25 / 294.25

Rotterdam 380 cSt

Nov17 332.25 / 334.25

Dec17 328.75 / 330.75

Jan18 328.00 / 330.00

Feb18 327.75 / 329.75

Mar18 327.50 / 329.50

Apr18 327.00 / 329.00

Q1-18 327.75 / 329.75

Q2-18 326.25 / 328.25

Q3-18 321.75 / 324.25

Q4-18 314.50 / 317.00

CAL18 320.50 / 323.50

CAL19 287.50 / 292.50

CAL20 256.75 / 263.75


Jurgen Gerdes, WinGD. WinGD signs global service agreement for TMS Cardiff Gas LNG carrier newbuilds  

WinGD will support six dual-fuel engines on three new LNG carriers for the Athens-based operator throughout their operational lives.

Yangze LNG 01 vessel. Yangzijiang Xinfu delivers first 175,000-cbm LNG carrier built by Chinese private shipyard  

Vessel features two dual-fuel MAN B&W 5G70ME-C10.5-GA-EGR engines fitted with cryogenic units.

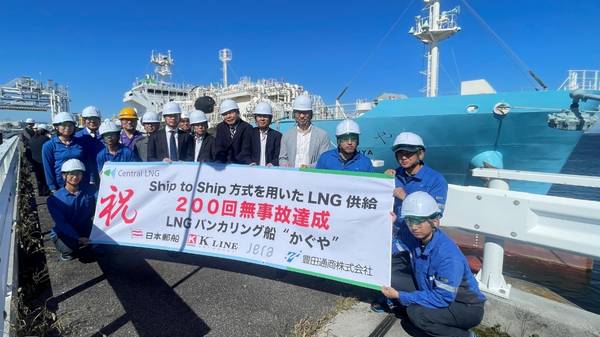
Kaguya 200th ship-to-ship (STS) LNG bunkering operation. LNG bunkering vessel Kaguya completes 200th ship-to-ship operation in Japan  

K Line’s joint venture vessel reaches milestone in Mikawa Bay.

MFM Nicole vessel. Synergy Marine adds dual-fuel LPG carrier to managed fleet  

MFM Nicole joins Synergy’s gas carrier portfolio as owners weigh fuel choices ahead of MEPC 85 negotiations.

CMA CGM Notre Dame vessel. DSV to use CMA CGM’s ACT+ solution to slash shipping emissions  

Danish firm targets 12,000-tonne reduction in CO₂ emissions over two years through the use of UCOME-based biofuels.

Peninsula 2026 graduate cohort. Peninsula welcomes 2026 graduate cohort across global bunkering network  

Bunker firm brings new graduates into roles spanning Houston, Singapore, Gibraltar, Monaco and Las Palmas.

Mathias Krogsgard, Malik Supply. Malik Supply appoints Mathias Krogsgård as bunker trader  

Danish bunker firm adds trader with export and technology background to growing team.

Jeroen De Vos, Peninsula. Biofuel adoption in shipping shifts from debate to delivery, says Peninsula's Jeroen de Vos  

Marine biofuels have moved from pilot projects to routine fuel strategy, argues IBIA vice-chair.

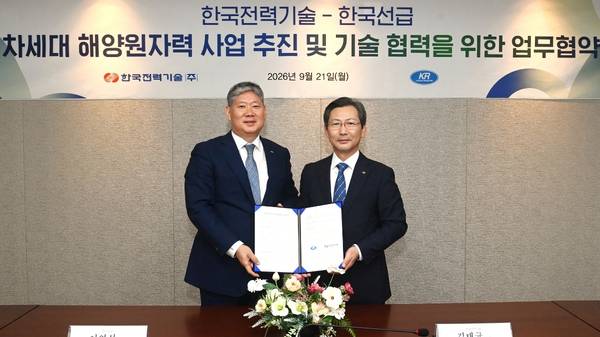
KEPCO E&C and KR signing. KEPCO E&C and Korean Register of Shipping to collaborate on marine SMR development  

Korean firms to develop technical standards and certification pathways for the BANDI offshore small modular reactor.

Ship-to-ship (STS) LNG bunkering operation at the Port of Sagunto. Peninsula completes first LNG bunkering operation at Sagunto  

Levante LNG bunkering vessel supplies K Line car carrier in landmark delivery.