Fri 3 Nov 2017, 08:44 GMT

Oil and fuel oil hedging market update


By the Oil Desk at Freight Investor Services.


Brent closed up $0.13 last night to $60.62 and WTI closed at $54.54, up $0.24. Well, once again, it's all rather rosy. Brent is up 2% on the week. On the month it's up 7.5% and on the year it is up 16%. I'm sure everyone who is at OPEC is giving themselves a massive pat on the back. The question is: will these levels be able to sustain themselves? Well, let's talk about that, shall we? Let's have OPEC in the Brent corner and the USA in the WTI corner for a second. OPEC production has been capped and Brent has risen 16% since that magical meeting. US production has risen by about 1.1mn bpd and prices have risen about 10% on WTI. So let me ask you this my fellow oilanauts, which one has the ability to maintain higher prices and higher production? I fear that the start of my commentary will soon lead with the price of WTI and not Brent. Has Brent had its day as the global benchmark? Perhaps not, perhaps it's even irrelevant, but let me tell you this: China have ramped up crude purchases in 2017 by 13% so far. The US are exporting more and more and are now starting to sell to the Chinese. The Middle East (OPEC really) has seen a sizeable drop in the number of cargoes purchased by China. Apparently, demand is increasing but pfff to that, this "increased demand" is nothing, but buyers making hay whilst WTI is $6 cheaper than Brent. Doesn't take a rocket scientist to work that out, does it? I wish you all a wonderful weekend.

Fuel Oil Market (November 2)

The front crack opened at -7.40, weakening to -7.50, strengthening to -7.45, ending the day at -7.55. The Cal 18 was valued at -7.55.

Asia's front-month East-West arbitrage spread slipped to a near-three week low on Thursday as Singapore onshore inventories of the industrial fuel climbed to an eight-week high.

The December arbitrage spread was also weighed down by recent strength in the Rotterdam market relative to Singapore, making fuel oil imports into Singapore from the European oil hub less economical, sources said.

Singapore inventories rose for a fourth straight week, up 2.5%, or 94,000 tonnes, from the previous week to 3.84 million tonnes in the week to Nov. 1. Weekly net imports into Singapore were down 31% from a week earlier to 0.88 million tonnes, a three-week low. Fuel oil stocks are now 12.6% higher year on year.

Economic Data/Events: (UK times)

* 12:30pm: U.S.

** Change in nonfarm payrolls for Oct., est. 313k (prior -33k)

** Unemployment rate for Oct., est. 4.2% (prior 4.2%)

** Trade balance for Sept., est. -$43.2b (prior -$42.4b)

* 2pm: U.S.

** Factory orders for Sept., est. 1.2% (prior 1.2%)

** Durable goods orders for Sept., final, est. 2% (prior 2.2%)

* 5pm: U.S. Baker Hughes weekly oil, gas rig counts

* 6pm: ICE weekly commitments of traders report for Brent, gasoil

* 7:30pm: U.S. CFTC weekly commitments of traders report on futures and options contracts

Singapore 380 cSt

Dec17 - 355.50 / 357.50

Jan18 - 353.25 / 355.25

Feb18 - 351.50 / 353.50

Mar18 - 349.75 / 351.75

Apr18 - 348.25 / 350.25

May18 - 346.75 / 348.75

Q1-18 - 351.50 / 353.50

Q2-18 - 346.75 / 348.75

Q3-18 - 341.25 / 343.75

Q4-18 - 336.00 / 338.50

CAL18 - 343.00 / 346.00

CAL19 - 307.75 / 312.75

Singapore 180 cSt

Dec17 - 360.25 / 362.25

Jan18 - 358.75 / 360.75

Feb18 - 357.00 / 359.00

Mar18 - 355.75 / 357.75

Apr18 - 354.75 / 356.75

May18 - 353.50 / 355.50

Q1-18 - 357.25 / 359.25

Q2-18 - 353.25 / 355.25

Q3-18 - 347.75 / 350.25

Q4-18 - 343.50 / 346.00

CAL18 - 349.75 / 352.75

CAL19 - 316.75 / 321.75

Rotterdam 380 cSt

Dec17 335.00 / 337.00

Jan18 333.00 / 335.00

Feb18 332.00 / 334.00

Mar18 331.00 / 333.00

Apr18 330.00 / 332.00

May18 328.75 / 330.75

Q1-18 332.00 / 334.00

Q2-18 329.00 / 331.00

Q3-18 323.50 / 326.00

Q4-18 315.25 / 317.75

CAL18 325.00 / 328.00

CAL19 286.00 / 291.00

BP  

Jurgen Gerdes, WinGD. WinGD signs global service agreement for TMS Cardiff Gas LNG carrier newbuilds  

WinGD will support six dual-fuel engines on three new LNG carriers for the Athens-based operator throughout their operational lives.

Yangze LNG 01 vessel. Yangzijiang Xinfu delivers first 175,000-cbm LNG carrier built by Chinese private shipyard  

Vessel features two dual-fuel MAN B&W 5G70ME-C10.5-GA-EGR engines fitted with cryogenic units.

Kaguya 200th ship-to-ship (STS) LNG bunkering operation. LNG bunkering vessel Kaguya completes 200th ship-to-ship operation in Japan  

K Line’s joint venture vessel reaches milestone in Mikawa Bay.

MFM Nicole vessel. Synergy Marine adds dual-fuel LPG carrier to managed fleet  

MFM Nicole joins Synergy’s gas carrier portfolio as owners weigh fuel choices ahead of MEPC 85 negotiations.

CMA CGM Notre Dame vessel. DSV to use CMA CGM’s ACT+ solution to slash shipping emissions  

Danish firm targets 12,000-tonne reduction in CO₂ emissions over two years through the use of UCOME-based biofuels.

Peninsula 2026 graduate cohort. Peninsula welcomes 2026 graduate cohort across global bunkering network  

Bunker firm brings new graduates into roles spanning Houston, Singapore, Gibraltar, Monaco and Las Palmas.

Mathias Krogsgard, Malik Supply. Malik Supply appoints Mathias Krogsgård as bunker trader  

Danish bunker firm adds trader with export and technology background to growing team.

Jeroen De Vos, Peninsula. Biofuel adoption in shipping shifts from debate to delivery, says Peninsula's Jeroen de Vos  

Marine biofuels have moved from pilot projects to routine fuel strategy, argues IBIA vice-chair.

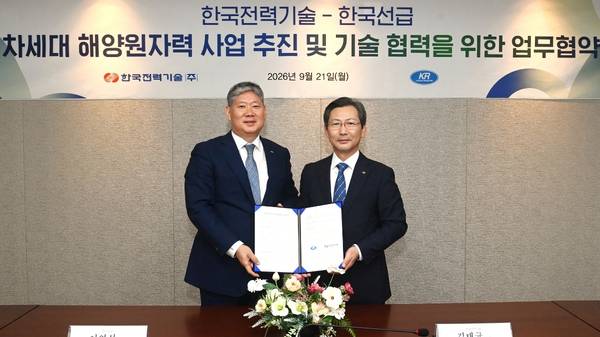
KEPCO E&C and KR signing. KEPCO E&C and Korean Register of Shipping to collaborate on marine SMR development  

Korean firms to develop technical standards and certification pathways for the BANDI offshore small modular reactor.

Ship-to-ship (STS) LNG bunkering operation at the Port of Sagunto. Peninsula completes first LNG bunkering operation at Sagunto  

Levante LNG bunkering vessel supplies K Line car carrier in landmark delivery.