Fri 27 Oct 2017, 09:05 GMT

Oil and fuel oil hedging market update


By the Oil Desk at Freight Investor Services.


Commentary

Brent closed up $0.86 last night to $59.30 and WTI closed at $52.64, up $0.46. Well, Brent is up 3.5% this week. Forwardddddd march! Up to $60, $70? Dare I say it, will $100 per bbl oil be on the most bullish of economists' forecasts soon? This market is brutal though. I mean, don't get me wrong, it is brilliant if you're a producer; they must be looking forward to next year's summer holidays already. But how is everyone else faring in this relentlessly bullish market? Trading margins seem so thin and there is no market structure to make anything work out further than 10 days, so perhaps next year it will be more of a greedy volume game as opposed to putting something in storage and relying on the market structure to do the work for you. Freight values seem to have gone a little haywire - even if the actual fixtures aren't there to back up the market's insatiable appetite for arbitrage spreads currently. Granted, new flat rates will be out soon and the fat cats at Worldscale are waiting to unleash 2018 numbers, so keep an eye over the next few weeks with an eye like Mad-Eye Moody.

Fuel Oil Market (October 26)

The front crack opened at -7.85, weakening to -8.05, during the Barges trading window. The Cal 18 was valued at -8.15.

Rising inventories in Singapore weighed on Asia's fuel oil crack, which slipped to a near two-week low but remained well within its recent trading range. The November 180 cSt fuel oil crack to Dubai crude narrowed to minus $2.41 a barrel, its narrowest discount since Oct. 10

Similarly, the November 180 cSt discount to Brent crude fell to $4.36 a barrel, its narrowest discount since Oct. 10.

Singapore's net exports of fuel oil to China topped the weekly list (279,000 tonnes); followed by Hong Kong (240,000 tonnes) and Indonesia (36,000 tonnes).

Largest Singapore net imports originated from Russia (527,000 tonnes); followed by the UAE (242,000 tonnes), Malaysia (214,000 tonnes), and Venezuela (146,000).

Economic Data/Events: (UK times)

* 7:45am: France consumer confidence for Oct., est. 101 (prior 101)

* 1:30pm: U.S. GDP annualized q/q for 3Q, advance, est. 2.6% (prior 3.1%)

* 3pm: U.S. University of Michigan sentiment for Oct., final, est. 100.7 (prior 101.1)

* 6pm: U.S. Baker Hughes weekly U.S. oil, gas rig counts

* 6pm: ICE weekly commitments of traders report

* 8:30pm: U.S. CFTC weekly commitments of traders report on futures and options contracts

** Africa oil week, final day

** Singapore International Energy Week, Day 5, including Nordic Green Dialogue

** Russia final Urals program for Nov.

** Earnings: Total, Eni SpA, Exxon Mobil, Chevron, Phillips 66, Imperial Oil

Singapore 380 cSt

Nov17 - 338.50 / 340.50

Dec17 - 337.25 / 339.25

Jan18 - 335.25 / 337.25

Feb18 - 333.75 / 335.75

Mar18 - 332.50 / 334.50

Apr18 - 331.25 / 333.25

Q1-18 - 334.00 / 336.00

Q2-18 - 330.00 / 332.00

Q3-18 - 325.75 / 328.25

Q4-18 - 321.75 / 324.25

CAL18 - 329.50 / 332.50

CAL19 - 298.50 / 303.50

CAL20 - 268.50 / 275.50

Singapore 180 cSt

Nov17 - 343.25 / 345.25

Dec17 - 342.25 / 344.25

Jan18 - 341.00 / 343.00

Feb18 - 340.25 / 342.25

Mar18 - 339.25 / 341.25

Apr18 - 338.25 / 340.25

Q1-18 - 340.25 / 342.25

Q2-18 - 336.75 / 338.75

Q3-18 - 332.50 / 335.00

Q4-18 - 329.50 / 332.00

CAL18 - 336.25 / 339.25

CAL19 - 307.25 / 312.25

CAL20 - 278.25 / 285.25

Rotterdam 380 cSt

Nov17 319.75 / 321.75

Dec17 316.25 / 318.25

Jan18 315.75 / 317.75

Feb18 315.50 / 317.50

Mar18 315.25 / 317.25

Apr18 314.75 / 316.75

Q1-18 315.50 / 317.50

Q2-18 314.00 / 316.00

Q3-18 309.50 / 312.00

Q4-18 302.25 / 304.75

CAL18 311.50 / 314.50

CAL19 278.50 / 283.50

CAL20 247.75 / 254.75


Jurgen Gerdes, WinGD. WinGD signs global service agreement for TMS Cardiff Gas LNG carrier newbuilds  

WinGD will support six dual-fuel engines on three new LNG carriers for the Athens-based operator throughout their operational lives.

Yangze LNG 01 vessel. Yangzijiang Xinfu delivers first 175,000-cbm LNG carrier built by Chinese private shipyard  

Vessel features two dual-fuel MAN B&W 5G70ME-C10.5-GA-EGR engines fitted with cryogenic units.

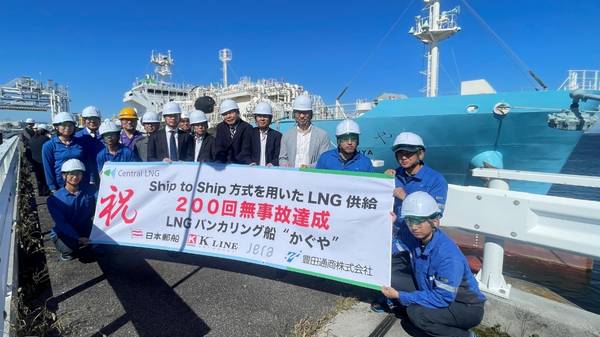
Kaguya 200th ship-to-ship (STS) LNG bunkering operation. LNG bunkering vessel Kaguya completes 200th ship-to-ship operation in Japan  

K Line’s joint venture vessel reaches milestone in Mikawa Bay.

MFM Nicole vessel. Synergy Marine adds dual-fuel LPG carrier to managed fleet  

MFM Nicole joins Synergy’s gas carrier portfolio as owners weigh fuel choices ahead of MEPC 85 negotiations.

CMA CGM Notre Dame vessel. DSV to use CMA CGM’s ACT+ solution to slash shipping emissions  

Danish firm targets 12,000-tonne reduction in CO₂ emissions over two years through the use of UCOME-based biofuels.

Peninsula 2026 graduate cohort. Peninsula welcomes 2026 graduate cohort across global bunkering network  

Bunker firm brings new graduates into roles spanning Houston, Singapore, Gibraltar, Monaco and Las Palmas.

Mathias Krogsgard, Malik Supply. Malik Supply appoints Mathias Krogsgård as bunker trader  

Danish bunker firm adds trader with export and technology background to growing team.

Jeroen De Vos, Peninsula. Biofuel adoption in shipping shifts from debate to delivery, says Peninsula's Jeroen de Vos  

Marine biofuels have moved from pilot projects to routine fuel strategy, argues IBIA vice-chair.

KEPCO E&C and KR signing. KEPCO E&C and Korean Register of Shipping to collaborate on marine SMR development  

Korean firms to develop technical standards and certification pathways for the BANDI offshore small modular reactor.

Ship-to-ship (STS) LNG bunkering operation at the Port of Sagunto. Peninsula completes first LNG bunkering operation at Sagunto  

Levante LNG bunkering vessel supplies K Line car carrier in landmark delivery.