Wed 25 Oct 2017, 08:47 GMT

Oil and fuel oil hedging market update


By the Oil Desk at Freight Investor Services.


Commentary

Brent closed up $0.96 last night to $58.33 and WTI closed at $52.47, up $0.57. Well, quite a rally we have on our hands, don't we? The question of course on everyone's lips is whether we can break through that magical $60 per bbl in time for every US oil producer to order a specially selected, organic, free range, bronze turkey with extra truffles for Thanksgiving. What am I talking about "order"? Probably buy a turkey farm, then use the cooked carcass to light up a Monte Cristo. I'm going to say this until I'm blue in the face, but with sustained rallies, the only real people who are benefitting are the US producers. I read yesterday that Utah seems to be the next state where the oil rush will gravitate towards, and the regulators of Utah are trying to streamline the issuance of licences. Wednesday is here, so another set of API data last night caused the market to celebrate, then commiserate at the same time. I think this week could be the last week where the last effects of hurricane season could perhaps skew numbers so I would err on the side of caution as always when stats are published. We had another "do whatever it takes" plea last night from the Saudi Oil minister yesterday, and I have to take my hat off to him. Since last year, the Saudi-led production cut has yielded a 25pct price increase. I don't care whether you live under a bridge and don't know how to spell - 25% is a good return. I don't see him giving up either, but as with anything, change is round the corner so keep your eyes on every OPEC minister over the coming weeks.

Fuel Oil Market (October 24)

The front crack opened at -7.65, strengthening to -7.60, before weakening to -7.80. The Cal 18 was valued at -8.25

Cash premiums of Asia's 180-cst high-sulphur fuel oil rose for a fifth straight session on Tuesday to a one-month high boosted by a surge in buying interest for the lower viscosity fuel oil that is typically characterised by low trade volumes.

The strong buying interest for 180-cst cargoes lifted cash premiums of the fuel to 97 cents a tonne, its highest since Sept. 21

The volume of 180-cst fuel oil changing hands on Tuesday is the highest daily traded volume for the lower viscosity fuel since at least the start of the year.

Economic Data/Events: (UK times)

* 12pm: U.S. MBA mortgage applications for week ended Oct. 20 (prior 3.6%)

* 1:30pm: U.S. durable goods orders for Sept., prelim., est. 1% (prior 2%)

* 3pm: U.S. new home sales for Sept., est. 554k (prior 560k)

* 3:30pm: EIA weekly oil inventory report

* Today:

** Singapore International Energy Week, 3rd day of 5, including Asia Clean Energy Summit

** Africa Oil Week, 3rd day of 5

** OPEC-EU dialogue meeting in Brussels

** Genscape weekly ARA crude stockpiles report

** Africa Oil Week, 2nd day of 5

** Genscape weekly ARA crude stockpiles report

** Russia Urals full month loading program for November

Singapore 380 cSt

Nov17 - 338.25 / 340.25

Dec17 - 336.75 / 338.75

Jan18 - 335.00 / 337.00

Feb18 - 333.50 / 335.50

Mar18 - 332.25 / 334.25

Apr18 - 331.00 / 333.00

Q1-18 - 333.50 / 335.50

Q2-18 - 330.00 / 332.00

Q3-18 - 326.00 / 328.50

Q4-18 - 322.00 / 324.50

CAL18 - 327.00 / 330.00

CAL19 - 296.00 / 301.00

CAL20 - 266.00 / 273.00

Singapore 180 cSt

Nov17 - 343.25 / 345.25

Dec17 - 342.00 / 344.00

Jan18 - 341.00 / 343.00

Feb18 - 339.75 / 341.75

Mar18 - 338.75 / 340.75

Apr18 - 337.75 / 339.75

Q1-18 - 339.75 / 341.75

Q2-18 - 336.75 / 338.75

Q3-18 - 332.50 / 335.00

Q4-18 - 329.50 / 332.00

CAL18 - 333.75 / 336.75

CAL19 - 304.75 / 309.75

CAL20 - 275.75 / 282.75

Rotterdam 380 cSt

Nov17 319.25 / 321.25

Dec17 315.00 / 317.00

Jan18 314.50 / 316.50

Feb18 314.25 / 316.25

Mar18 314.00 / 316.00

Apr18 313.50 / 315.50

Q1-18 314.25 / 316.25

Q2-18 312.75 / 314.75

Q3-18 308.75 / 311.25

Q4-18 302.00 / 304.50

CAL18 308.75 / 311.75

CAL19 276.75 / 281.75

CAL20 246.00 / 253.00


Jurgen Gerdes, WinGD. WinGD signs global service agreement for TMS Cardiff Gas LNG carrier newbuilds  

WinGD will support six dual-fuel engines on three new LNG carriers for the Athens-based operator throughout their operational lives.

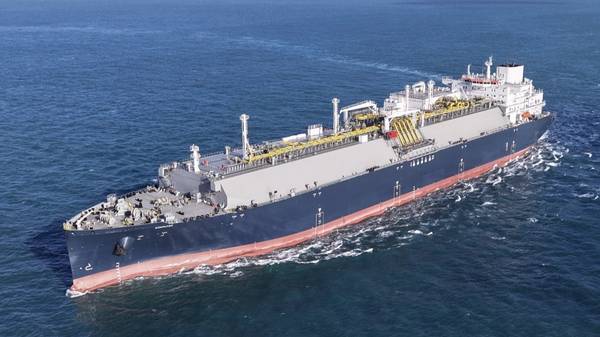
Yangze LNG 01 vessel. Yangzijiang Xinfu delivers first 175,000-cbm LNG carrier built by Chinese private shipyard  

Vessel features two dual-fuel MAN B&W 5G70ME-C10.5-GA-EGR engines fitted with cryogenic units.

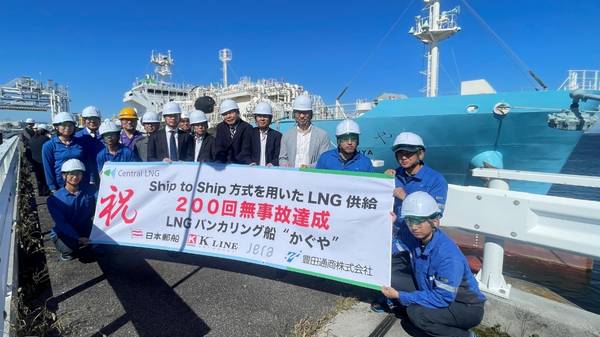
Kaguya 200th ship-to-ship (STS) LNG bunkering operation. LNG bunkering vessel Kaguya completes 200th ship-to-ship operation in Japan  

K Line’s joint venture vessel reaches milestone in Mikawa Bay.

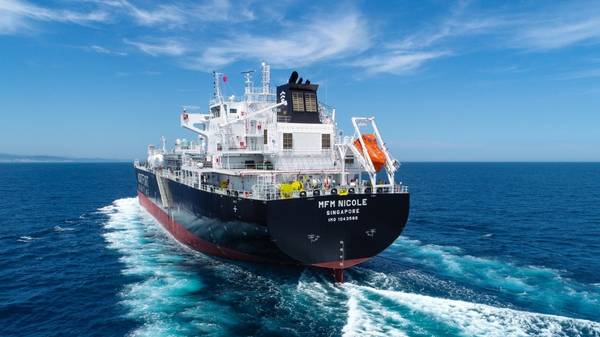
MFM Nicole vessel. Synergy Marine adds dual-fuel LPG carrier to managed fleet  

MFM Nicole joins Synergy’s gas carrier portfolio as owners weigh fuel choices ahead of MEPC 85 negotiations.

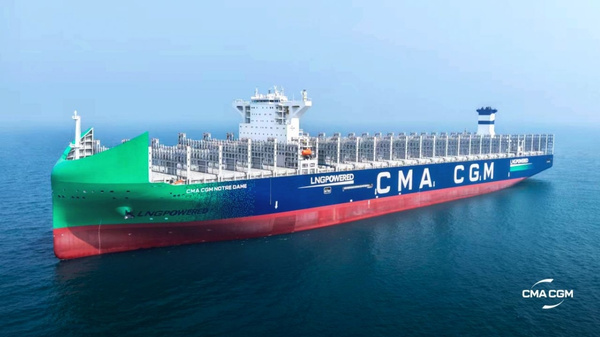
CMA CGM Notre Dame vessel. DSV to use CMA CGM’s ACT+ solution to slash shipping emissions  

Danish firm targets 12,000-tonne reduction in CO₂ emissions over two years through the use of UCOME-based biofuels.

Peninsula 2026 graduate cohort. Peninsula welcomes 2026 graduate cohort across global bunkering network  

Bunker firm brings new graduates into roles spanning Houston, Singapore, Gibraltar, Monaco and Las Palmas.

Mathias Krogsgard, Malik Supply. Malik Supply appoints Mathias Krogsgård as bunker trader  

Danish bunker firm adds trader with export and technology background to growing team.

Jeroen De Vos, Peninsula. Biofuel adoption in shipping shifts from debate to delivery, says Peninsula's Jeroen de Vos  

Marine biofuels have moved from pilot projects to routine fuel strategy, argues IBIA vice-chair.

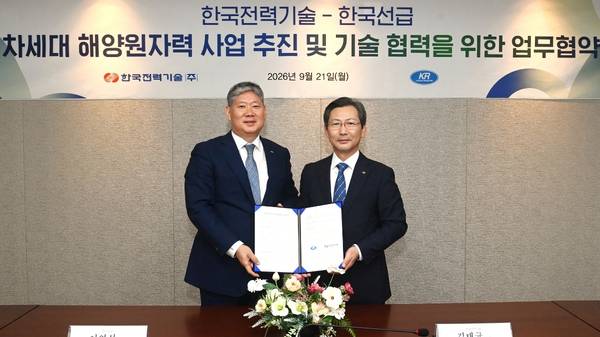
KEPCO E&C and KR signing. KEPCO E&C and Korean Register of Shipping to collaborate on marine SMR development  

Korean firms to develop technical standards and certification pathways for the BANDI offshore small modular reactor.

Ship-to-ship (STS) LNG bunkering operation at the Port of Sagunto. Peninsula completes first LNG bunkering operation at Sagunto  

Levante LNG bunkering vessel supplies K Line car carrier in landmark delivery.